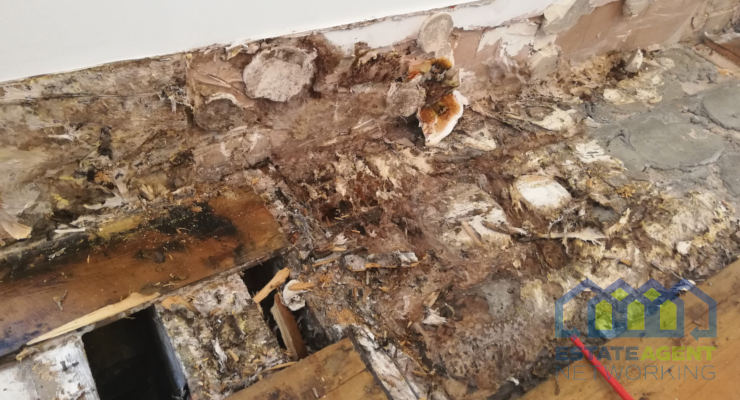
Is your home purchase blighted by flood risk?
Did you know that one in six homes in Britain is at risk of flooding? Contrary to popular belief, these aren’t just properties close to rivers or by the sea; over 3 million homes are at risk from flooding because of surface water, blocked drains or overflowing sewers.
If you are looking to buy residential property, it’s a good idea to establish the flood risk at an early stage, so you can take the right decision on whether to proceed with the purchase or simply walk away. Not only can flooding, if it happens, affect your enjoyment of the new home and put your personal possessions at risk, you also need to consider the impact on your home insurance, not to mention the ability to obtain a mortgage for the purchase in the first place.
Also take into account that a flood risk property may be difficult to sell, and while you may be fine with your dream cottage having an unpredictable stream at the bottom of the garden, a history of flooding, high insurance premiums and restricted mortgage opportunities could deter prospective buyers in the future.
How can you find out about the flood risk?
If you’ve found your dream home, your first port of call should be the seller or estate agent to find out if any part of the building has ever flooded. However, susceptibility to flooding is not always apparent and your seller may only have a limited knowledge of the property, especially if they haven’t lived there long.
Once your offer is accepted, there are several ways you can find about the property’s flooding history.
- Pre-contract enquiries and searches
Your conveyancer will ask the seller about flooding in their standard pre-contract enquiries and you could be liable for compensation if the seller knowingly gives false information. Make sure that the formal conveyancing papers contain all the necessary answers, and that these have been checked by your lawyer.
Your solicitor will carry out a number of searches on the property as part of the purchasing process. Environmental searches will include maps published by the Environment Agency to show generic information about local flood risks from watercourses and surface water, while the Land Registry also gives a flood risk indicator.
It can be a huge disappointment to discover that your prospective new home is in a high flood risk area. While your solicitor won’t be able to change the facts, he can however ensure that all the right searches and enquiries are obtained, while liaising with your building surveyor, putting you in the best possible situation to make the right decision.
- Building Surveys
While standard searches can give a good general indication of the likely flood risk in your area, the advice given is not building specific, so further investigation may be required to satisfy all concerned parties. Your lender’s mortgage valuation may also raise concerns if a risk of flooding is detected.
For your own peace of mind, it is recommended that you have a professional building survey carried out by a RICS regulated surveyor, ideally someone who can delve deep to compile a specialist flood survey, or has the right experience and equipment to survey waterside properties.
Not only can an in-depth home survey give you a better understanding of the possible impact of flooding on your new home, it can also give useful advice on how to physically reduce the risk of flooding.
How will your home insurance by affected?
While a heightened risk of flooding need not necessarily stop you from proceeding with the purchase of the home of your dreams, it’s prudent to know the risks involved. One of the major considerations when you’re thinking of buying a home in a flood risk area is whether you’ll be able to get buildings insurance and the type of cover available to you.
If you’re buying the building with a mortgage, your lender will insist on adequate buildings insurance to commence from exchange of contracts to cover their risk. You can take out home insurance to cover you for any damage caused by floods, but reasonably priced insurance cover may be hard to come by if the property has been identified as being at risk. Some research will be needed to find the best deal.
You may be able to take advantage of Flood Re, the government backed scheme that makes it easier for home owners with high flood risk properties to obtain insurance cover on reasonable terms. Do check your assumptions that you can get cover before you proceed with the property purchase – not all types of property are eligible.
Although it’s not yet standard practice for insurance companies to take account of flood resilience measures, it is something the industry will be moving towards. While this should eventually translate into savings for homeowners who have taken the right precautions, for now it’s up to you to consider your options before you commit to the property.
You May Also Enjoy

Alterations can change a property’s rebuild cost

HMO conversions hit investors for £82,000 on average
Selling a HAUNTED house?
Renters call for greater transparency in HMOs
Housing Insight Report: August 2026