


The Sun Continues to Shine on UK Construction
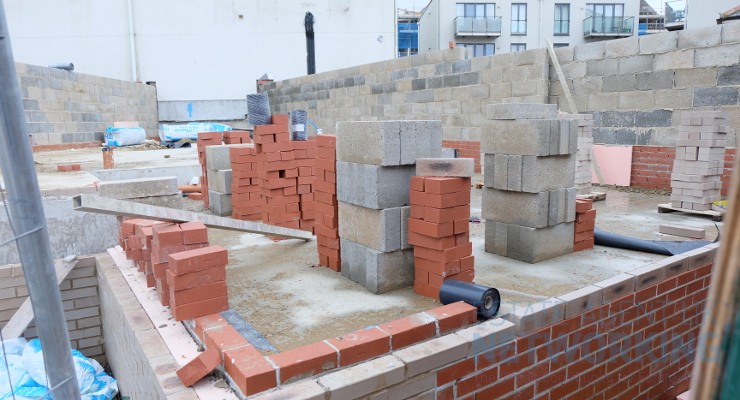
Glenigan’s July Index shows the industry continuing to bask in the glow of better performance
Work starting on-site increased 49% during the three months to June, remaining 25% above 2024 levels
Residential construction starts rocketed 76% compared to the preceding three months and rose 64% against 2024 figures
Despite ending 3% down on a year ago, non-residential project starts increased 21% against the preceding three months
Civils work starting on-site increased 6% against the preceding three months but decreased 30% against the previous year
Today, Glenigan | Powered by Hubexo, one of the construction industry’s leading insight experts, releases the July 2025 edition of its Construction Index.
The Index focuses on the three months to the end of June 2025, covering all underlying projects, with a total value of £100m or less (unless otherwise indicated), with figures seasonally adjusted.
It’s a report which provides a detailed and comprehensive analysis of year-on-year construction data, giving built environment professionals a unique insight into sector performance over the last 12 months.
The July Index comes hot on the heels of Glenigan’s positive summer 2025 Forecast, published last month. Following a similar pattern to the latter, which predicts a 24% performance uptick over the next two years, the July Index reveals a surge in construction starts.
Displaying all the signs of an industry-wide recovery, and building on growing momentum in Q.2, work starting on site increased by an impressive 49% over Q.2, finishing 25% above 2024 levels.
In what will come as welcome news to contractors, developers and subcontractors nationwide, the big winner in the July Index was undoubtedly the Residential sector, with the private vertical posting exceptionally strong results. Overall, it saw starts soar over three quarters (+76%) against the preceding three months and by almost two-thirds (+64%) compared to last year.
This surge is due to the commencement of various residential schemes. One standout example is the £72.9 million Westland Heath development in Sudbury, Suffolk. Comprising 206 houses and 36 flats (242 units in total), this project significantly helped accelerate growth in the sector.
Whilst slightly more modest, non-residential construction rose 21% against the previous three months. However, this increase wasn’t quite enough to put it in the black when compared to 2024 (-3%).
Regionally the South East, South West, North West, North East, and the West Midlands were all significantly up against both Q.2 and last year. Overall growth was driven by increased sector activity in the South East. The £56.9 million Portchester Phase 1 development in Hampshire, including 135 houses and 45 flats (180 units in total) was a key contributor supporting the underlying growth.
Commenting on the July 2025 Index, Glenigan’s Economic Director, Allan Wilen, says, “We’re seeing confidence returning at a much faster pace than anyone ever expected. It’s almost hard to believe when you look at how sluggish activity was in Q.4 2024 and Q.1 2025. However, these results, largely bolstered by a flurry of starts in the residential sector, bear out the predictions our economics unit made in its recent industry forecast.
“Whilst recovery is a little slower in the non-residential sector, predominantly civils, the various strategies being introduced by the Government and the recent Spending Review promise to deliver on a large scale. No doubt, as capital spending is released and critical projects are greenlit, we’ll see further revival across these verticals.”
Sector Analysis – Residential
Residential construction starts experienced very strong growth during the Index period, increasing 76% compared to the preceding three months and 64% against 2024 figures.
Private housing was the main growth-driver, rising a stratospheric 95% against the preceding three months, experiencing an 84% increase on the year before. Whilst social housing did increase 11% against the preceding three months, it finished 4% down on the previous year.
Sector Analysis – Non-Residential
Whilst the non-residential sector presented more of a mixed picture, there were plenty of bright spots to celebrate.
Health experienced a strong period, rising 41% against the preceding three months to stand 29% higher than the previous year. Offices also experienced a relatively strong period, rising 36% against the preceding three months and remaining 8% above the previous year. The commencement of various schemes in both verticals helped support overall growth.
Hotel & Leisure followed a similar trend, rising 9% against the preceding three months and remaining 13% above the previous year.
However, whilst other verticals experienced growth against the Index period, these increases weren’t quite enough to put them on par, or above, 2024 levels.
Retail increased 5% against the preceding three months to stand 24% down against the previous year. Education also experienced a mixed period, rising 31% against the preceding three months but declining 24% against the previous year.
Civils work starting on-site increased 6% against the preceding three months but decreased 30% against the previous year. Infrastructure work starting on-site increased 2% against the preceding three months and decreased by 38% against the previous year. Utilities starts also had a mixed performance, rising 11% against the preceding three months to stand 17% down against the previous year.
Anomalous, Community and amenity project starts declined 4% against the preceding three months but increased 53% against the previous year.
Regional Outlook
Regional performance was particularly strong over Q.2 2025.
The South West experienced a strong performance, increasing 31% against the preceding three months to stand 26% up against the previous year. The North West performed similarly, rising 72% against the preceding three months and rising 23% against the previous year. The South East also performed well, rising 53% against the preceding three months to stand 39% up against the previous year.
Not to be outdone, the North East experienced a strong performance, increasing 75% against the preceding three months to stand 26% up against the previous year. The West Midlands increased 78% against the preceding three months to stand 83% up against the previous year.
Whilst London rose 34% against the preceding three months, it finished 10% down against the previous year. Similarly, performance was mixed across the remaining regions.
You May Also Enjoy

Why landlords selling up is a tax story, not a regulation story

27 November tipped for biggest pre-Christmas moving rush

UK property transaction growth stalls in 2026

What Makes a Commercial Property Attractive to Modern Businesses?

Sellers lower price expectations further
